A bank valuation shortfall means your lender has valued the property below your agreed purchase price, and it will only lend against that lower figure, leaving you to cover the gap. The priority is speed: call your broker or lender today, confirm your finance clause deadline, and ask whether an extension or internal review is possible before that date passes. Acting promptly after a valuation shortfall protects both your deposit and your options.
TL;DR:
- Check the full report against your contract and building report, then challenge errors in bedrooms, land size, parking, condition, or renovations.
- Support a formal dispute with settled nearby sales from the past three to six months, documented adjustments, and a written response timeline from the lender.
- At an $800,000 purchase price and a $740,000 valuation, an 80% loan falls by $48,000, and the higher LVR may trigger or increase LMI.
- If the dispute fails, consider cash, a family guarantee, seller renegotiation, a larger deposit, or a second lender, then compare repayment and LMI costs.
- Missing the finance clause deadline can forfeit termination rights and put your deposit at risk, so request any extension in writing.
Table of Contents
- Why do bank valuations sometimes come in lower than the contract price?
- How to calculate the shortfall and its effect on your borrowing power
- Step-by-step: how to challenge a low bank valuation
- Practical fallback options if your challenge does not succeed
- Contract implications, finance clause timing and settlement risk
- How a buyers agent manages a valuation shortfall in practice
- What buyers get wrong under pressure
- How we help when your valuation comes in short
- FAQ
Why do bank valuations sometimes come in lower than the contract price?
Lenders commission valuations to protect their own exposure, not to confirm what you agreed to pay. A valuer working for the bank tends toward caution, and that conservatism is often the point of the exercise rather than a flaw in it. Several factors commonly push a valuation below the purchase price, according to explanations of conservative lender approaches to valuation.
- Weak or outdated comparable sales in the immediate area
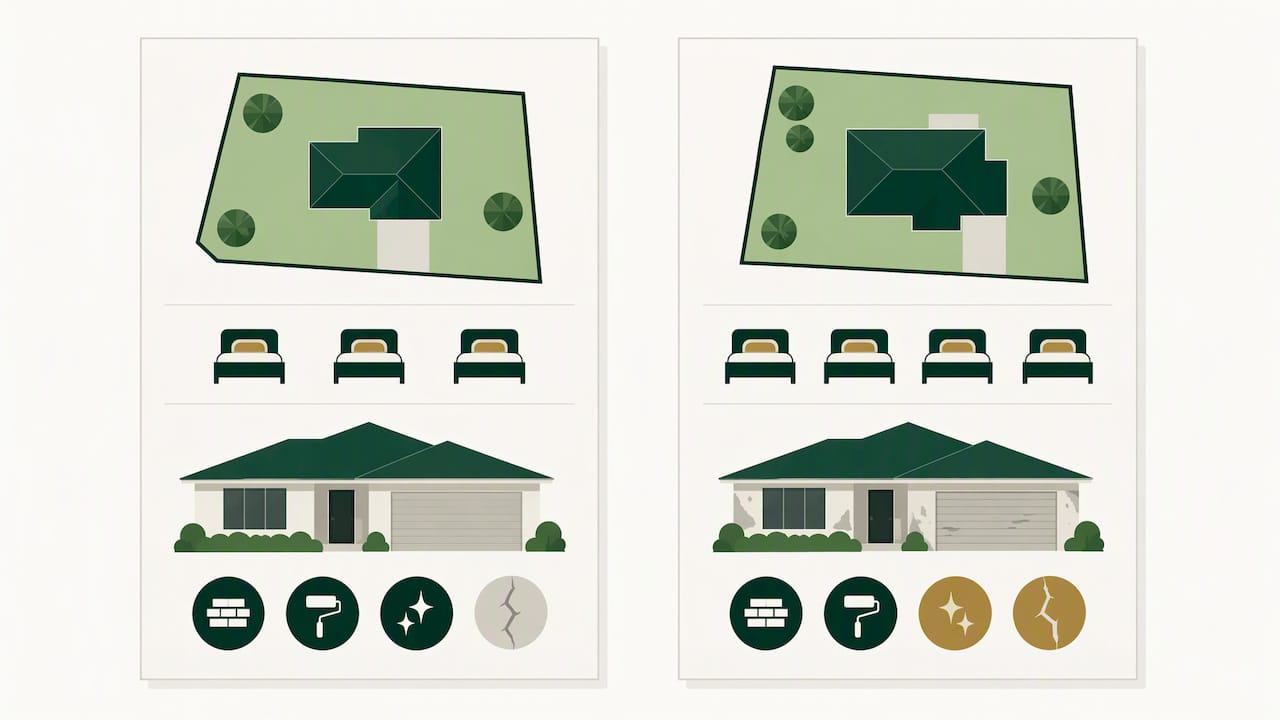
- Incorrect property details on file, such as land size or bedroom count
- Condition issues or deferred maintenance the valuer has flagged
- Recent market movement that the data has not yet caught up with
- Volatility specific to off the plan purchases or regional postcodes
Many lenders also lean on automated valuation models for a first pass, and those models can be blunt instruments in suburbs with limited recent sales. Before you do anything else, read the valuation report line by line and check it against your contract and building report.
Pro Tip: Compare the valuer’s stated land size, bedroom count and condition notes against your contract of sale before assuming the figure itself is wrong.
How to calculate the shortfall and its effect on your borrowing power
The shortfall is simply the gap between what you agreed to pay and what the bank is willing to lend against. Here is a worked example, using illustrative figures only.
- Say you agreed to buy a property for $800,000.
- The bank’s valuation comes back at $740,000.
- The shortfall is $60,000, the difference between the two figures.
- If you were borrowing 80% of the purchase price ($640,000), the lender now calculates 80% of the lower valuation instead, around $592,000.
- You now need to find an extra $48,000 in cash, on top of your original deposit, to bridge the gap.
A lower valuation also pushes your loan to value ratio (LVR) higher relative to the new figure, which can tip you over the threshold where Lenders Mortgage Insurance (LMI) applies, or increase the premium if you are already paying it. That is a second cost shock on top of the cash shortfall itself, and it is worth asking your broker to model both numbers before you decide your next move.
Step-by-step: how to challenge a low bank valuation
A formal dispute process exists with most lenders, and it works best when you move quickly and methodically. Guidance on contesting a low appraisal points to comparables and factual accuracy as the two levers that matter most.
- Request a copy of the full valuation report, not just the figure, and check every factual detail: bedrooms, bathrooms, land size, parking and any recent renovations.
- Pull together settled sales (not current listings) from the past three to six months, ideally within easy walking distance, using tactics for sourcing comparable sales in Sydney.
- Adjust each comparable for condition, orientation and land size, and support your adjustments with photos or agent notes where you have them.
- Lodge a formal dispute with the lender, attaching the corrected facts and comparables, and ask for a written timeline on when you will hear back.
- If the internal review does not move the figure, commission an independent valuation from a separate certified valuer and submit it alongside your dispute or to a new lender.
- Ask your broker to approach a different lender for a fresh valuation if the first result still looks out of step with the market.
Pro Tip: Settled sales carry far more weight with a valuer than current listings, so lead your comparables with the most recent completed sales you can find.
Practical fallback options if your challenge does not succeed
If the dispute process does not close the gap, you still have several workable paths, each with different cash and timing trade-offs described in common options for bridging an appraisal gap.
- Pay the shortfall in cash if you have the funds available, which keeps the purchase on track without changing lenders.
- Arrange a family guarantee or additional security, which some lenders accept in place of extra cash, though it adds a guarantor’s property to the risk.
- Seek a second opinion valuation from a different lender, understanding this can take several days to weeks depending on the valuer’s availability.
- Negotiate the purchase price down with the seller, using the valuation itself as evidence, with tactics covered in our guide to negotiating a Sydney house price.
- Increase your deposit if your savings or a top up from family can stretch to it, which lowers your LVR back toward the original lending tier.
Each of these affects your monthly repayment and your LMI exposure differently, so it is worth asking your broker to run the numbers before you commit to one path. Reviewing typical deposit levels for Sydney properties can help you judge whether a cash top up is realistic for your situation.
Contract implications, finance clause timing and settlement risk
Your finance clause is the clock you are racing against, and it matters more than almost any other date in the contract once a shortfall appears. Most NSW contracts allow termination for genuine failure of finance, but only within the clause’s deadline and only when you can evidence the failure properly, as set out in our finance clause checks before exchange.
- Confirm the exact finance clause deadline in your contract today, not from memory.
- Ask your broker or solicitor whether you can request a written extension, and what evidence the lender or vendor’s solicitor will want to see.
- Keep every piece of correspondence with your lender as proof of a genuine finance failure, not just a change of mind.
- Avoid letting the deadline pass silently: a missed clause can forfeit your right to terminate and put your deposit at risk.
How a buyers agent manages a valuation shortfall in practice
When a valuation comes back short, the first moves matter more than the eventual outcome. A buyers agent typically commissions a rapid independent appraisal, pulls fresh comparables, and opens a parallel conversation with both the seller’s agent and the lender, rather than waiting on one process at a time. That kind of simultaneous pressure, backed by access to off market stock and experience negotiating at auction, is often what turns a shortfall into a renegotiated price rather than a lost deposit.
A rapid, documented review of the lender’s valuation report for factual errors is the highest value first action, because many disputes succeed simply by correcting basic mistakes in bedrooms, lot size or recent renovations.
What buyers get wrong under pressure
The biggest mistake we see is hesitation: buyers wait for the lender to call back instead of pushing the dispute and the seller conversation at the same time. Two things matter most, document everything in writing, and move before your finance clause deadline, not after.
— Kristan
How we help when your valuation comes in short
We represent buyers only, never sellers, which means our entire focus sits on protecting your position when a valuation falls short. Our Complete Purchase Solution covers independent appraisal, due diligence and negotiation end to end, while our Negotiation Only service steps in if you have already found the property and just need an experienced advocate at the table.
- We commission independent appraisals quickly so you have real evidence to put to the lender or seller.
- We negotiate directly with agents and vendors, including at auction, where our auction bidding experience helps avoid overpaying in the first place.
- A small retainer at engagement is deducted from the final balance, with the remainder payable only on a completed purchase.
| Service | What it covers |
|---|---|
| Complete Purchase Solution | Strategy, search, appraisal, due diligence, negotiation, settlement |
| Negotiation Only | Representation once you have identified a property |
| Auction Bidding | Experienced bidding to avoid overpaying at auction |
Call us on 1800 676 177 or visit our services page to talk through your shortfall before your finance clause deadline passes.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What can I do if the bank valuation is too low for my property?
Check the valuation report for factual errors first, then gather recent settled comparable sales and lodge a formal dispute with your lender. If that does not resolve it, consider an independent valuation, a second lender opinion, topping up cash, or renegotiating price with the seller.
How much does it cost to get a bank valuation?
Lenders typically arrange the initial valuation as part of your loan application, often at no separate charge to you, though an independent or second opinion valuation usually carries its own fee. Costs and timeframes vary by valuer and lender, so ask your broker for current figures before commissioning one.
What does a low valuation mean for my purchase?
It means the lender will only lend against the lower figure, not your agreed purchase price, leaving you responsible for the difference in cash or through another arrangement. It also raises your loan to value ratio, which can trigger or increase Lenders Mortgage Insurance.
How accurate is a bank valuation?
Bank valuations lean conservative by design, since lenders use them to manage their own risk rather than to reflect market sentiment. A valuer typically relies on a handful of comparable sales, so accuracy depends heavily on how recent and relevant those comparables are to your property.
Recommended
- US Investors Face NSW Land Tax Once Land Value Exceeds A$1,075,000
- Section 32 explained: what Sydney buyers need to know
- US Buyers: Buy Sydney Property Sight Unseen Without Getting Burned
- Five Business Days: What NSW Buyers Must Do Before the 5pm Cutoff